AI in Finance and Banking (2026): What Works, What the Evidence Shows, and the Risks
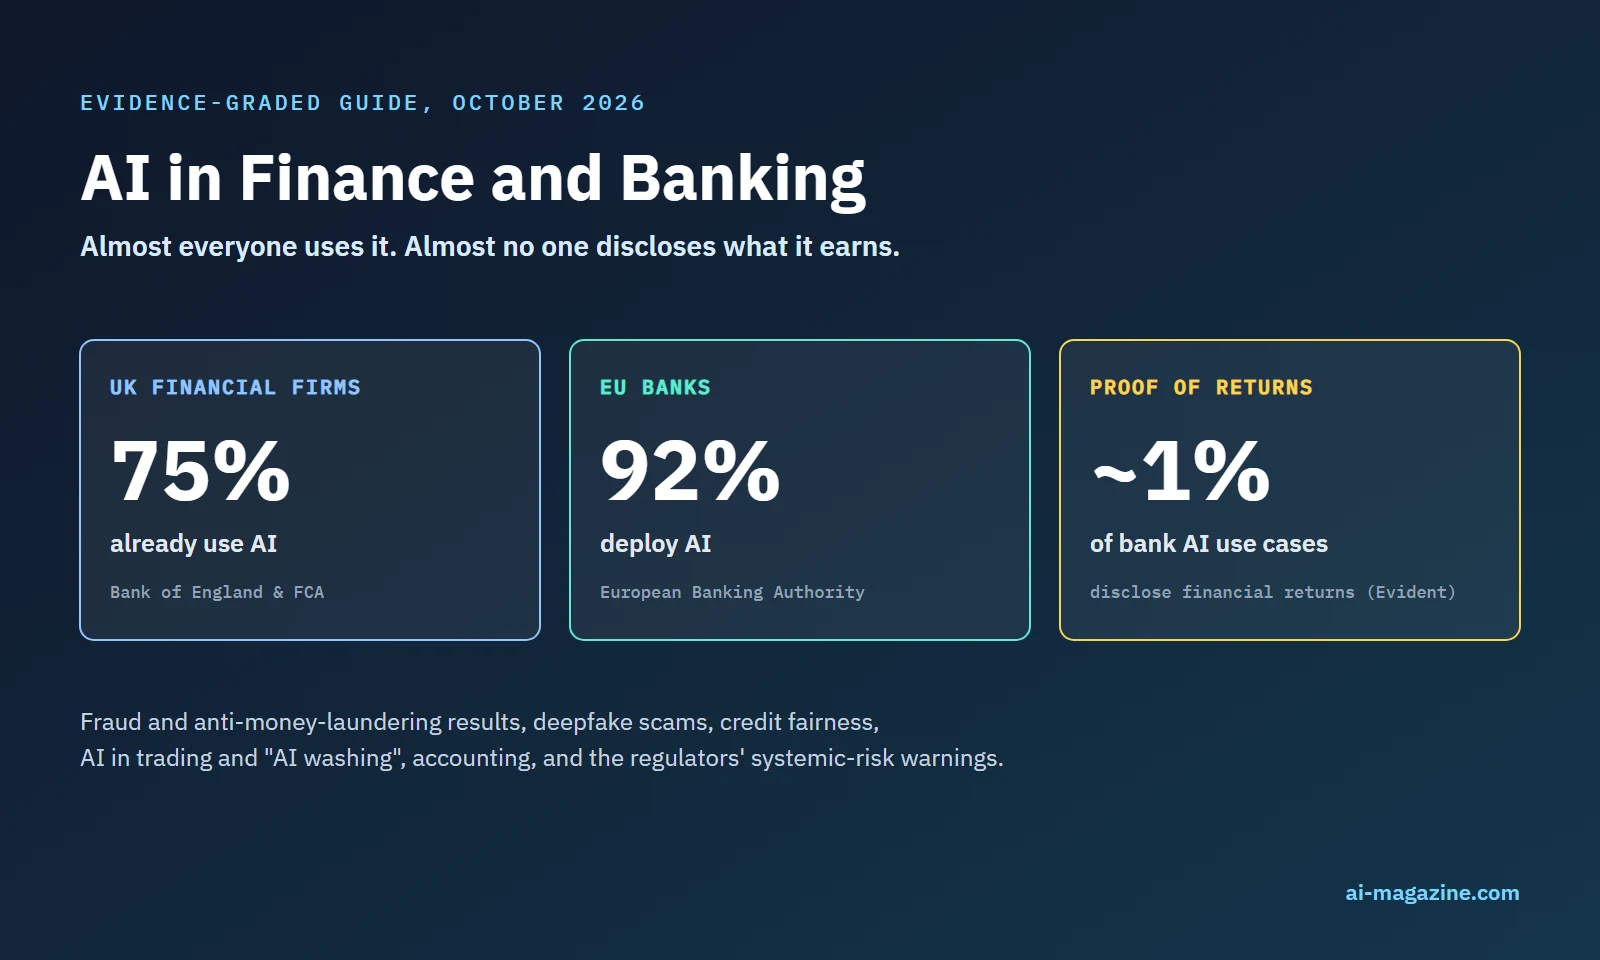
AI in finance is the use of machine learning and generative AI to detect fraud, assess credit, serve customers, analyze markets and automate back-office work in banks, insurers, payment companies and investment firms. By late 2026, the technology has moved from experimental pilots to core infrastructure, with major regulators reporting that 75% of surveyed firms in the UK are already using it and 92% of EU banks are deploying it. Yet a significant gap remains between this widespread adoption and the proof of economic value: according to Evident’s 2026 AI Index of 50 large banks, only about 12% of bank AI use cases report impact against operational KPIs, and roughly 1% disclose concrete financial returns. This guide separates regulator data, academic research and company claims, and covers what works, how criminals use AI, credit fairness, “AI washing” in trading and the systemic risks regulators worry about. Nothing here is investment advice.
How AI is used in finance
AI is applied across nearly every function in modern financial institutions, though the maturity of implementation varies widely. The primary use cases include:
- Fraud and scam detection: Machine learning models analyze transaction patterns in real time to identify anomalies, such as unusual spending locations or rapid-fire small transactions that indicate card testing.
- Anti-money laundering (AML): Algorithms scan vast volumes of transaction data to flag suspicious activity, reducing the manual workload for compliance officers by filtering out false positives.
- Customer service assistants: Generative AI chatbots and voice assistants handle routine inquiries, account updates, and basic troubleshooting, freeing human agents for complex issues.
- Credit scoring and underwriting: Models assess borrower risk using traditional data and alternative data sources, such as cash flow patterns, to make faster lending decisions.
- Trading and investment research: Algorithms execute trades based on quantitative signals, while natural language processing tools summarize earnings calls and news to assist portfolio managers.
- Risk management and compliance: AI models help monitor exposures and support regulatory reporting, with humans accountable for the results.
- Accounting and back office: Generative AI assists with document processing, reconciliation, and report generation, reducing manual entry errors and processing times.
- Employee copilots and coding assistants: Internal tools help developers write code faster and assist analysts in drafting reports, reviewing contracts, and synthesizing data.
Who uses AI in finance: adoption in numbers
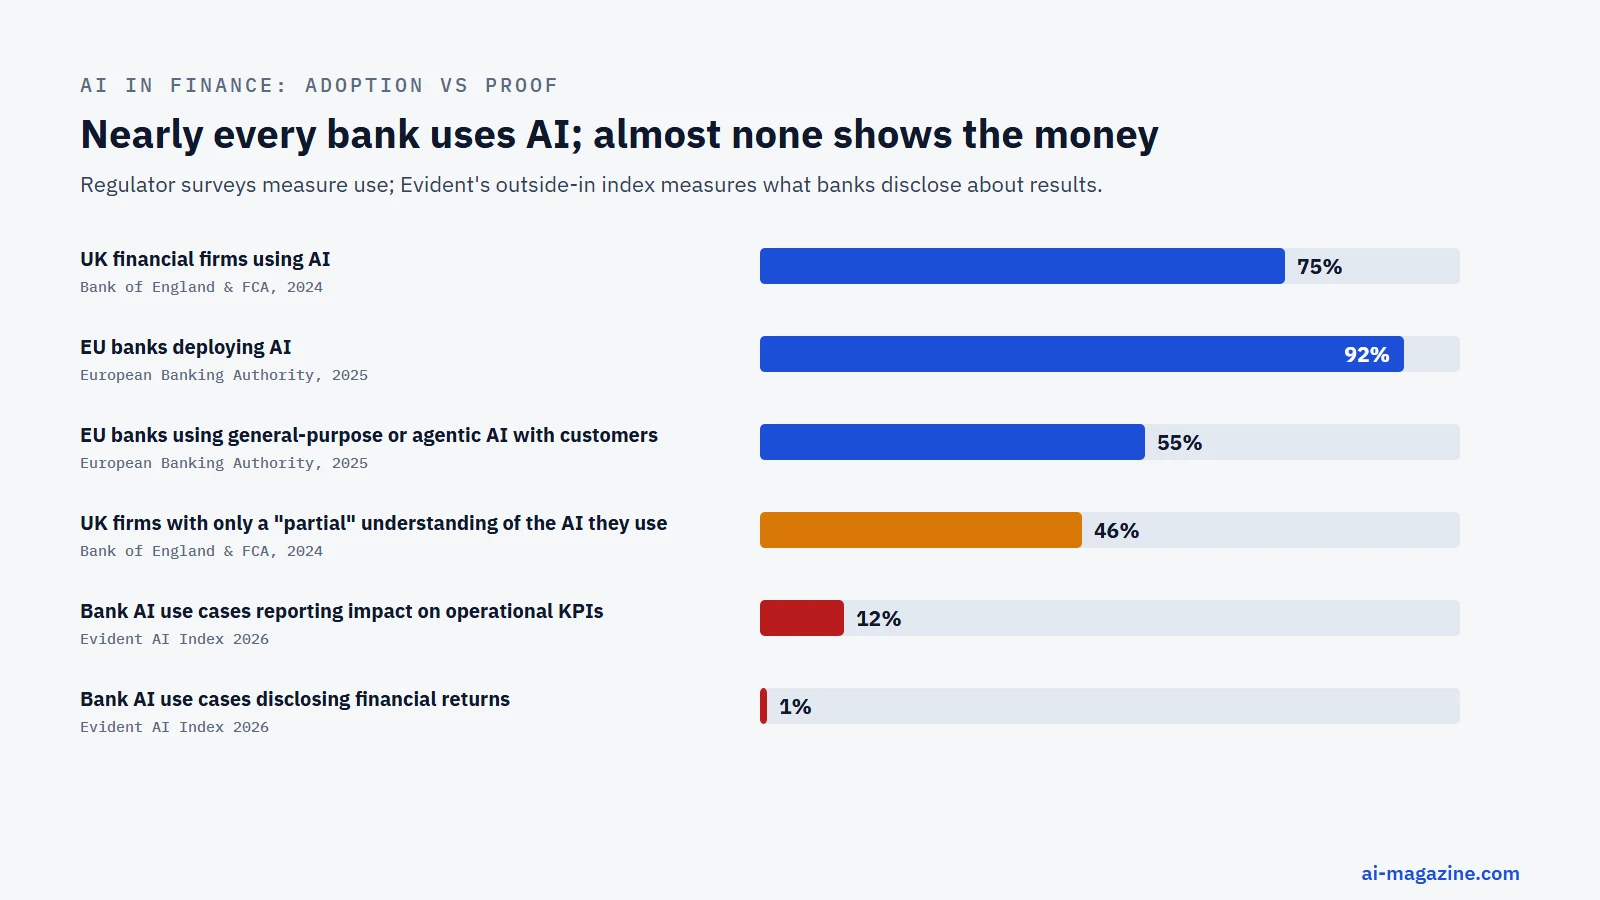
Regulatory surveys provide the most reliable snapshot of current adoption levels, though they often reveal a disconnect between usage and understanding. The Bank of England and Financial Conduct Authority (FCA) published a survey in November 2024 covering 118 firms, finding that 75% of firms are already using artificial intelligence, with a further 10% planning to adopt it within three years. This represents a significant increase from 2022, when only 58% of firms reported using AI. The survey also noted that foundation models account for 17% of AI use cases, and a third of these use cases are implemented by third parties. Notably, 46% of firms report only a “partial” understanding of the AI they use, and only 2% of use cases are fully autonomous.
In Europe, the European Banking Authority (EBA) reported in September 2025 that 92% of EU banks are currently deploying AI. The EBA highlighted that 55% of surveyed banks are already using General Purpose AI (GPAI) or agentic AI in consumer-facing processes. The authority identified reliance on third parties and reputational and litigation risks as a result of hallucinations as key challenges.
Despite high adoption rates, verifying actual business value remains difficult. The Evident AI Index 2026, which ranks 50 large banks based on public information, found that JPMorgan Chase held the top spot for the fifth year, followed by Capital One and RBC. However, Evident noted that only about 12% of bank AI use cases report impact against operational KPIs, and only about 1% disclose concrete financial returns. This discrepancy suggests that many institutions are using AI for efficiency gains that are hard to quantify, rather than direct revenue generation. Company-reported value is often hard to verify because institutions define “value” differently, and many pilots never scale to full production.
How the big banks use AI
Major financial institutions are leading the charge in AI deployment, using the technology to drive efficiency and enhance customer experiences. The figures below are the banks’ own; none has been independently audited.
JPMorgan Chase
JPMorgan Chase has been a consistent leader in AI adoption. The bank’s internal Large Language Model (LLM) Suite reached 200,000 onboarded users in just eight months. In February 2026, the bank stated that 150,000 people use the suite every week, estimating that it saves them about four hours a week per user. CEO Jamie Dimon highlighted the financial impact in October 2025, stating, “for $2 billion of expense, we have about $2 billion of benefit.” In his April 2026 letter to shareholders, Dimon added that “AI will definitely eliminate some jobs, while it enhances others,” and warned that AI introduces “serious new risks — from deepfakes and misinformation to cybersecurity vulnerabilities.”
In its investment bank, over 90% of engineers use AI coding assistants, accelerating development cycles. Additionally, AI-based transaction screening reviews more than double the volume of transactions while halving manual operator checks, significantly improving efficiency in compliance operations.
Bank of America and Morgan Stanley
Bank of America’s digital assistant, Erica, remains a cornerstone of its customer service strategy. In 2025, 20.6 million users interacted with Erica nearly 700 million times, bringing the total number of interactions since its 2018 launch to more than 3.2 billion. Erica predates today’s generative AI; it is the longest-running large-scale AI assistant in US retail banking.
Morgan Stanley has integrated AI into its wealth management advisory process. Over 98% of its financial-advisor teams use its OpenAI-based AI @ Morgan Stanley Assistant. The figure counts advisor teams, not individual users, but it shows how quickly generative AI became a standard tool in wealth management.
Goldman Sachs and the copilot wave
Goldman Sachs accelerated its AI adoption in June 2025 by rolling out its GS AI Assistant firmwide. This move signaled a shift towards enterprise-wide generative AI tools, similar to trends seen in other tech-forward firms. The “copilot wave” refers to the broader industry trend of embedding AI assistants directly into employee workflows, enhancing productivity across roles from coding to customer service.
AI against fraud and money laundering
Fraud prevention is one of the most mature and measurable applications of AI in finance. Financial institutions use AI to detect anomalies in real time, reducing losses from unauthorized transactions and complex scams.
Card networks and payment processors
Card networks and payment processors handle billions of transactions daily, making manual monitoring impossible. AI models analyze transaction patterns to identify fraud with high speed and accuracy. Visa says it blocks about $40 billion a year in attempted fraud. Mastercard states that modeling shows its generative-AI fraud system, Decision Intelligence Pro, raises detection rates by 20% on average. Stripe reports that its payments foundation model raised the detection of card-testing attacks on large users from 59% to 97%. These are company figures, measured in different ways, so they cannot be compared with one another.
Anti-money laundering
Anti-money laundering (AML) is a critical compliance area where AI is reducing the burden on financial institutions. HSBC worked with Google Cloud on an AML AI system; in Google’s 2023 announcement, HSBC reported that its AI identified 2–4 times more suspicious activity while cutting alert volumes by more than 60%. This efficiency gain allows compliance teams to focus on high-risk cases rather than sifting through false positives. The ability to process larger volumes of data with fewer alerts is a key driver for AI adoption in AML.
Scam prevention
Scams are evolving, with criminals using AI to create more convincing phishing emails and deepfake videos. Commonwealth Bank of Australia reported that customer scam losses fell by 50% and customer-reported frauds fell by 30% in 2024, crediting new scam-detection tools that include generative-AI suspicious-transaction alerts. Later releases indicated that scam losses fell by 70% over two years. The bank credits several tools, of which AI alerts are one, so the drop cannot be attributed to AI alone.
AI as a weapon: deepfakes and AI-powered scams
The same technology banks use for defense is helping criminals. Generative AI makes convincing fake voices, videos and documents cheap, and lets scammers personalize messages at scale. The U.S. Federal Trade Commission reported that consumers lost $15.9 billion to fraud in 2025 across 3 million reports, a sharp increase from over $12 billion in 2024. Investment scams remained the largest category, accounting for $7.9 billion of those losses. The FTC does not break losses down by whether AI was involved, so the share of AI-enabled fraud is unknown.
High-profile corporate breaches illustrate the financial stakes. In 2024, engineering firm Arup lost approximately US$25 million after an employee in Hong Kong authorized 15 wire transfers following a video call with deepfaked versions of the company’s CFO and colleagues. The audio and video were convincing enough to bypass standard verification protocols. This incident highlights a critical vulnerability: trust in media is no longer guaranteed. In November 2024, the U.S. Financial Crimes Enforcement Network (FinCEN) issued a warning about rising suspicious-activity reports involving deepfake media, specifically noting fake identity documents used to bypass identity checks.
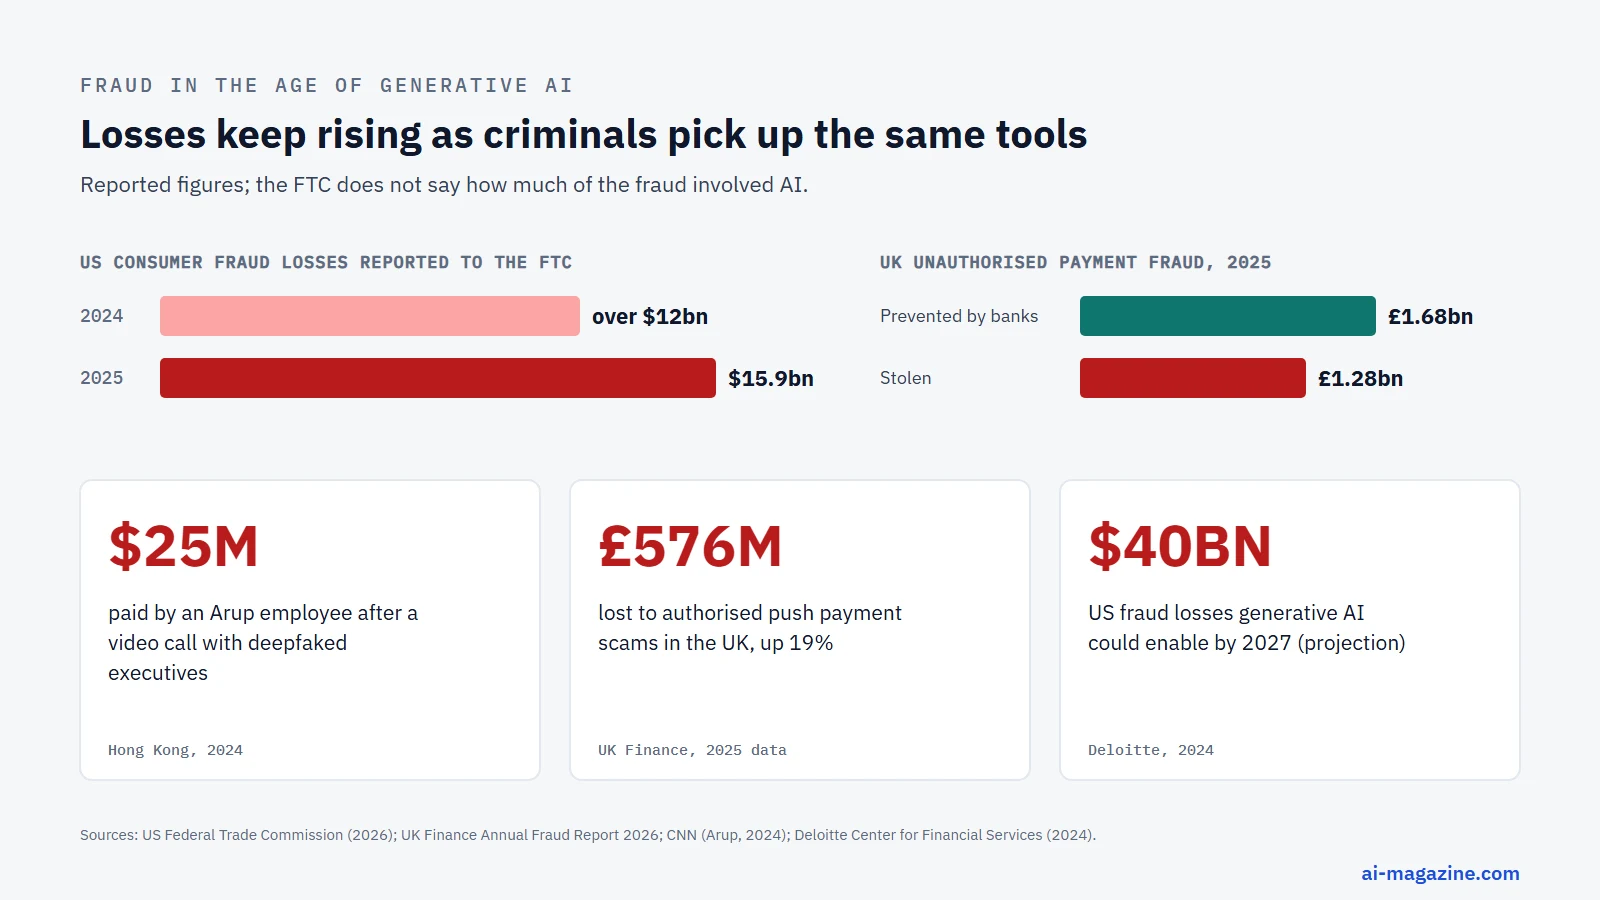
The scale of the threat is projected to grow. Deloitte projected in 2024 that generative AI could push U.S. fraud losses to $40 billion by 2027, up from $12.3 billion in 2023, representing a 32% annual growth rate. While this is a projection, the mechanism is already visible in retail banking. In the UK, the industry body UK Finance reported in its 2026 Annual Fraud Report that banks prevented £1.68 billion of unauthorized payment fraud in 2025, covering 70p in every £1 attempted. However, £1.28 billion was still stolen. Authorized push payment scam losses rose 19% to £576.4 million. The report explicitly warns that criminals are using AI to scale attacks and that deepfakes are being used in account opening.
The arms race between fraudsters and defenders is intensifying. As AI makes voice and video forgery cheaper and faster, the burden of verification shifts back to human judgment or more complex biometric checks. Banks are not just reacting; they are building predictive models to identify patterns before funds move. Yet, the Arup case and the FTC’s data show that when AI is used offensively, it exploits the speed of modern transfers. The key differentiator is no longer just detection speed, but the ability to distinguish synthetic media from reality in real-time.
AI in credit and lending: faster decisions, fairness questions
AI has transformed credit underwriting by processing non-traditional data points, but it has not solved the problem of bias. A study by Bartlett, Morse, Stanton, and Wallace published in the Journal of Financial Economics found that mortgage lenders charged Latinx and African-American borrowers 7.9 and 3.6 basis points more, respectively, for purchase and refinance mortgages. The researchers also noted that FinTech algorithms discriminated 40% less than face-to-face lenders in pricing, though FinTechs did not discriminate in loan approval decisions. This suggests AI can reduce human prejudice but may encode historical biases present in training data.
Regulatory scrutiny remains intense. The U.S. Consumer Financial Protection Bureau (CFPB) issued circulars in 2022 and 2023 stating that using complex algorithms does not excuse lenders from providing specific, accurate reasons for denying credit. In May 2025, the CFPB withdrew those circulars, but the underlying legal requirement under the Equal Credit Opportunity Act (ECOA) to provide specific reasons remains in force. Lenders must still ensure their AI models are explainable enough to meet this legal standard.
The high-profile Apple Card case illustrates the complexity of algorithmic fairness. In 2021, New York’s financial regulator reviewed approximately 400,000 applications and found no unlawful gender discrimination in the card’s credit decisions. However, in October 2024, the CFPB ordered Apple and Goldman Sachs to pay over $89 million for failures in handling customer disputes, not for bias. The CFPB terminated Apple’s order in September 2025. The case underscores that technical fairness in scoring does not guarantee procedural fairness in customer service.
Globally, regulation is tightening. The EU AI Act classifies AI used to assess creditworthiness or set life and health insurance prices as “high-risk.” Following the 2026 Digital Omnibus amendment, these obligations apply from 2 December 2027. Banks must ensure transparency, data governance, and human oversight for these systems. The European Banking Authority reported in September 2025 that 55% of surveyed banks are already using General Purpose AI (GPAI) or agentic AI in consumer-facing processes. They list reliance on third parties and reputational/litigation risks from “hallucinations” as key challenges. As AI becomes central to lending, the tension between speed and explainability will define the next era of credit.
AI in trading and investing: what’s real and what’s “AI washing”
Algorithmic trading is a large part of modern markets, but the label “AI” is often applied loosely. No reliable current regulator figure exists for the exact share of algorithmic trading, though Coalition Greenwich estimated in 2023 that about 37% of U.S. equity volume was executed via algorithms or smart order routers. The distinction between simple rule-based automation and machine learning-driven decisions is frequently blurred in marketing materials.
Recent research highlights both the potential and the limits of AI in prediction. Lopez-Lira and Tang, in a revised 2025 paper, found that GPT-4 sentiment scores on news headlines predicted next-day stock returns, especially for small stocks and negative news. However, they noted that “strategy returns decline as LLM adoption rises,” suggesting that as more players use similar AI models, the alpha diminishes.
The International Monetary Fund (IMF) warned in its October 2024 Global Financial Stability Report that AI could bring “greater volatility in times of stress.” AI-driven ETFs were observed to turn over holdings about once a month and showed herd-like selling during stress periods. The IMF noted that AI’s share of algorithmic-trading patent applications rose from 19% in 2017 to over 50% each year since 2020. This concentration of logic increases systemic risk. The Bank for International Settlements (BIS) stated in June 2024 that AI “could amplify procyclicality and market volatility by exacerbating herding.” The BIS also noted that “only a few companies provide cutting-edge LLMs” and that LLMs “cannot distinguish what is linguistically probable from what is factually correct.”
This gap between marketing and reality has led to regulatory action. The SEC has pursued several “AI washing” cases. In March 2024, investment advisers Delphia and Global Predictions paid $400,000 in total for false claims about using AI; Global Predictions had called itself the “first regulated AI financial advisor.” In January 2025, the SEC brought its first AI-washing case against a public company, Presto Automation. In April 2025, prosecutors charged the founder of the shopping app Nate with fraud, alleging its claimed AI automation rate was “effectively 0%.” These cases signal that vague claims about “AI-powered” features will face scrutiny.
Investors should approach apps promising AI stock picks with skepticism. While AI can process vast amounts of data, it does not inherently possess predictive superiority. The SEC withdrew its proposed rule on predictive data analytics in June 2025, indicating a preference for case-by-case enforcement over broad new rules. The core risk is that retail investors may confuse correlation with causation in AI-generated signals.
AI in accounting and finance teams
The adoption of AI in accounting is accelerating, driven by the need for efficiency in repetitive tasks. A Thomson Reuters Institute 2026 report, surveying over 1,500 professionals in legal, tax, accounting, and other fields, found that 40% of organizations now use generative AI, up from 22% previously. Despite this widespread adoption, only 18% of respondents say they track return on investment for these tools. This suggests a gap between implementation and measurable value.
The “Big Four” accounting firms have made significant financial commitments to AI, though these are company claims. PwC announced a $1 billion investment over three years in 2023. EY committed $1.4 billion to EY.ai in 2023. KPMG announced at least $2 billion over five years with Microsoft in 2023. They are announcements of intended spending, not audited results.
AI is particularly effective in high-volume, low-complexity tasks. Generative AI can draft journal entries, match invoices to purchase orders, and flag anomalies in general ledger accounts. However, human review remains critical. AI models can hallucinate, especially when dealing with unstructured data like contracts or emails. The value of AI in accounting lies not in replacing accountants, but in shifting their focus from data entry to analysis and advisory.
Systemic risks and regulation
Concentration and herding
As AI adoption grows, so does the risk of systemic concentration. The Financial Stability Board (FSB) identified in November 2024 that AI vulnerabilities include third-party dependencies, service-provider concentration, market correlations, cyber risks, and model risk. If many banks use the same third-party AI provider, a failure or bias in that model could affect the entire sector simultaneously.
The Bank of England Financial Policy Committee (FPC) warned in April 2025 that systemic risk could arise “if common weaknesses in widely used models cause many firms to misestimate certain risks.” The FPC also highlighted the risk of disruption at third-party AI providers. The Bank of England and FCA survey (published November 2024) found that a third of AI use cases are third-party implementations. Furthermore, the top three providers account for 73% of cloud, 44% of model, and 33% of data providers named. This concentration creates a single point of failure for the financial system.
The rules in 2026
Regulation is evolving to address these risks. The EU AI Act, effective from 2 December 2027 for credit and insurance, imposes strict transparency and governance requirements. The EU’s Digital Operational Resilience Act (DORA), effective from January 2025, provides direct oversight of critical ICT providers. In November 2025, European supervisors designated 19 critical providers, reportedly including AWS, Google Cloud, and Microsoft.
In the U.S., the SEC and FINRA are adapting existing rules. FINRA’s 2026 oversight report added a generative-AI section covering hallucinations, bias, cyber risk, and AI-enabled account takeover. Existing supervision and recordkeeping rules apply to AI agents. The US Treasury report (December 2024, 103 responses) advised firms to review AI use cases for compliance with existing laws before deployment. The FSB and BIS continue to monitor cross-border risks, emphasizing that AI can amplify volatility in times of stress. Regulators are not creating a new legal framework from scratch but applying existing principles to new technologies.
FAQ
How is AI used in finance?
AI is used for fraud detection, credit scoring, algorithmic trading, and customer service. Banks use it to analyze vast datasets for patterns in transactions and to automate routine tasks like reconciliation. While adoption is high, only a small percentage of use cases currently report concrete financial returns.
How do banks use AI?
Banks use AI to screen transactions for suspicious activity, process loan applications, and power chatbots like Bank of America’s Erica. JPMorgan Chase uses AI to assist engineers and screen transactions. However, reliance on third-party providers is common, with a third of use cases being third-party implementations.
Can AI predict the stock market?
AI can identify patterns in news sentiment and historical data, but it does not guarantee accurate predictions. Research shows that strategy returns can decline as more AI models adopt similar signals, leading to herding. AI can also amplify market volatility during stress periods.
Is AI used to detect fraud?
Yes, AI is widely used to detect fraud. Visa says it blocks about $40 billion in attempted fraud a year, and Mastercard and Stripe report higher detection rates; these are company figures. However, AI-powered scams, like deepfakes, are also rising, requiring continuous adaptation.
Are AI trading apps legit?
Some are legitimate software, but there is no public evidence that retail AI trading apps beat the market, and the SEC has fined firms for “AI washing”, meaning false claims about using AI. Be skeptical of any app that promises AI-driven stock picks or guaranteed returns.
Will AI replace jobs in finance?
AI will likely eliminate some routine jobs while enhancing others. JPMorgan Chase’s CEO stated that AI will definitely eliminate some jobs while enhancing others. Tasks like data entry and basic analysis are being automated, shifting human roles toward oversight and strategy.
Is AI in finance regulated?
Yes, regulation is evolving. The EU AI Act classifies credit scoring as high-risk, with obligations starting in 2027. In the US, the SEC and FINRA are enforcing existing rules on bias and recordkeeping. The FSB and BIS highlight concentration and systemic risks as key regulatory concerns.